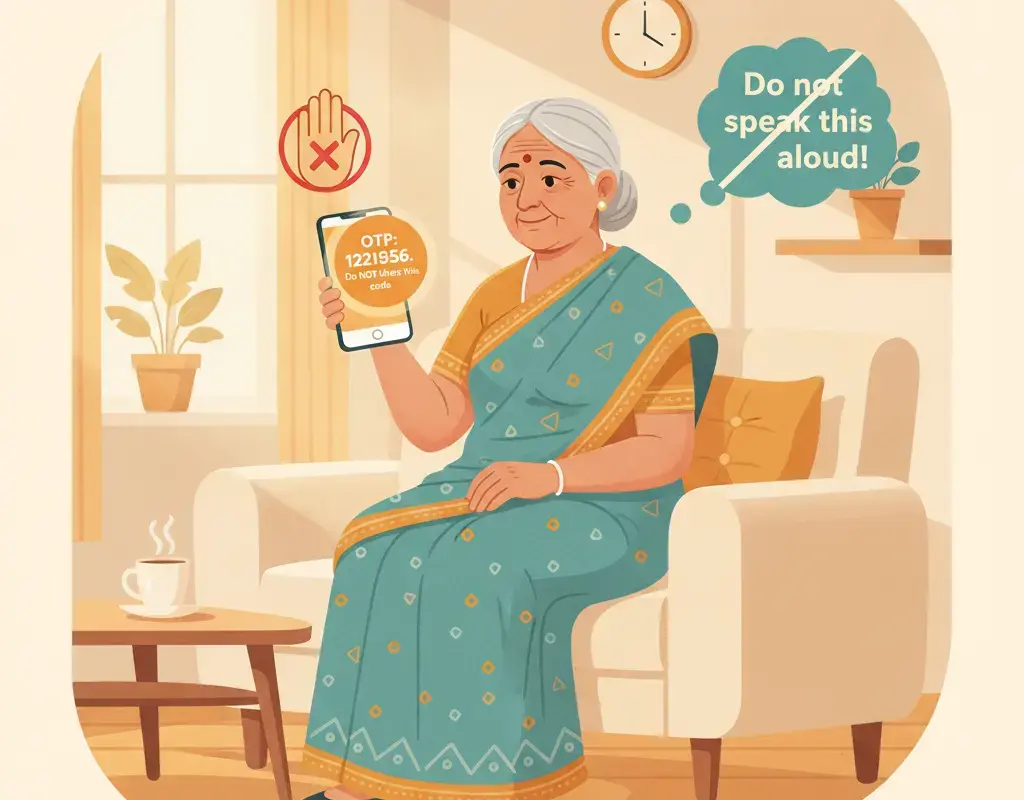
The Difference Between OTP and UPI PIN
Understand the difference between OTP and UPI PIN for secure digital transactions. Learn how OTP vs UPI PIN impacts your online banking safety.
Quick answer: OTP (One-Time Password) is a temporary code sent to your registered mobile number or email for verification during transactions, whereas a UPI PIN is a 4 or 6-digit personal code you set up for authorizing UPI-based payments.
Understanding the difference between OTP and UPI PIN is crucial for safe digital transactions in India. Many people often confuse “OTP vs UPI PIN,” but they serve different purposes in the online payment process.
While both are essential for secure banking, knowing when and how to use OTP and UPI PIN can help prevent fraud and protect your financial information.
Key takeaways
- OTPs are temporary and expire after use.
- UPI PIN is a permanent code you create and use for UPI transactions.
- OTPs enhance security by verifying your identity.
- UPI PIN is specific to your UPI account and linked bank account.
- Never share your UPI PIN or OTP with anyone.
What is an OTP and how is it used in transactions?
What is an OTP and how is it used in transactions?
OTP stands for “One-Time Password,” and it is a crucial security feature used in online and digital transactions in India. An OTP is a unique, temporary code sent to your registered mobile number or email address, typically valid for a short period, often between 5 to 15 minutes. The primary purpose of an OTP is to add an extra layer of security to your transactions, ensuring that even if someone has your password or other personal information, they cannot complete a transaction without this temporary code.
OTPs are widely used in various types of transactions, including:
- Online banking and financial transactions
- E-commerce purchases
- Password resets
- Two-factor authentication (2FA) for apps and services
For example, when you make a purchase on an e-commerce platform or conduct a banking transaction through a mobile app, you will receive an OTP to confirm your identity. This process is known as two-factor authentication (2FA), which combines something you know (like a password) with something you have (like your mobile device) to verify your identity.
Here’s a simple comparison of OTP with other security measures:
| Feature | OTP | Password | UPI PIN |
|---|---|---|---|
| Temporary | Yes | No | No |
| Requires Physical Device | Yes (mobile/email) | No | Yes (mobile) |
| Usage Frequency | One-time | Repeated | Repeated |
It’s important to remember that OTPs should never be shared with anyone. Scammers often try to trick individuals into sharing their OTPs through phishing attacks or fake calls. Always be cautious and verify the source before entering your OTP. If you suspect any fraudulent activity, report it immediately to the cybercrime division through the official portal at cybercrime.gov.in or by calling 1930.
By understanding how OTPs work and their role in securing your transactions, you can better protect yourself against potential fraud and unauthorized access to your accounts.
How does a UPI PIN differ from an OTP?
Understanding the difference between a UPI PIN and an OTP is crucial for safe digital transactions in India. Both are security measures, but they serve different purposes and function in distinct ways.
UPI PIN stands for Unified Payments Interface Personal Identification Number. It is a 4-6 digit numeric code that you set up when you first register for a UPI app like Google Pay, PhonePe, or Paytm. This PIN is unique to each UPI app and is used to authenticate and authorize transactions directly from your bank account. Whenever you send money or make a payment using UPI, you will be prompted to enter your UPI PIN. It is important to remember that your UPI PIN should never be shared with anyone, including bank officials or customer service representatives.
OTP, or One-Time Password, is a temporary code sent to your registered mobile number or email address. It is typically a 4-6 digit numeric code that is valid for a single transaction or a short period of time. OTPs are commonly used for verifying your identity during online transactions, such as when you make a purchase on an e-commerce site or when you reset your password. Unlike the UPI PIN, an OTP is not something you set yourself; it is generated by the system and sent to you each time it is required.
Here are some key differences between a UPI PIN and an OTP:
- Usage: UPI PIN is used for authorizing transactions within UPI apps, while OTP is used for verifying your identity in various online transactions.
- Generation: UPI PIN is set by the user and stored securely within the app, whereas OTP is generated by the system and sent to you via SMS or email.
- Validity: UPI PIN is permanent until you change it, while OTP is temporary and valid only for a single use or a short duration.
- Security: Both are secure, but UPI PIN is more like a password you use frequently, while OTP is a one-time code that adds an extra layer of security.
In the context of scams, never share your UPI PIN or OTP with anyone. Scammers often try to trick you into revealing these details by posing as bank officials or customer service agents. If you receive a call or message asking for your UPI PIN or OTP, it is likely a scam. Always verify the source and contact your bank directly through official channels if you have any doubts.
For more information on digital safety and to report cybercrimes, you can visit the official Indian cybercrime portal or call the national helpline at 1930.
| Factor | UPI PIN | OTP |
|---|---|---|
| Usage | UPI transactions | Various online transactions |
| Generation | Set by user | System-generated |
| Validity | Permanent until changed | Single use or short duration |
| Security | High | High |
Why is it important to keep your UPI PIN and OTP secure?
Why is it important to keep your UPI PIN and OTP secure?
In today’s digital age, financial transactions have become incredibly convenient with the advent of Unified Payment Interface (UPI) and One-Time Passwords (OTPs). However, this convenience comes with the responsibility of ensuring the security of your financial information. Keeping your UPI PIN and OTP secure is crucial to protect yourself from falling victim to various cybercrimes, including phishing, UPI fraud, and identity theft.
Your UPI PIN is a personal identification number that acts as a password for authorizing transactions through UPI apps. If someone gains access to your UPI PIN, they can easily transfer funds from your bank account without your consent. Similarly, OTPs are temporary codes sent to your registered mobile number or email to verify your identity during financial transactions. If a fraudster gets hold of your OTP, they can potentially complete unauthorized transactions, leading to significant financial loss.
Here are some reasons why securing your UPI PIN and OTP is essential:
- Prevent Unauthorized Transactions: Keeping your UPI PIN and OTP confidential ensures that only you can authorize transactions from your bank account.
- Protect Personal Information: Secure handling of OTPs and UPI PINs helps safeguard your personal and financial information from being compromised.
- Avoid Financial Loss: Unauthorized access to your accounts can lead to financial loss, which can be devastating for individuals and families.
- Maintain Trust in Digital Transactions: By securing your credentials, you contribute to maintaining trust in digital banking systems, encouraging more people to adopt these convenient services.
To better understand the differences between UPI PIN and OTP, consider the following table:
| Factor | UPI PIN | OTP |
|---|---|---|
| Purpose | Authorize transactions on UPI apps | Verify identity during transactions |
| Validity | Persistent until changed | Valid for a single transaction or a short period |
| Security Risk | High if compromised | High if intercepted |
| Protection Measures | Do not share, change periodically | Do not share, do not store |
Remember, if you suspect any unauthorized activity or receive suspicious messages asking for your UPI PIN or OTP, report it immediately to your bank and the cybercrime division at cybercrime.gov.in or by calling 1930. Stay vigilant and protect your digital financial life.
What should you do if you accidentally share your UPI PIN or OTP?
If you accidentally share your UPI PIN or OTP, it’s crucial to act quickly to protect your finances and prevent unauthorized transactions. Here are the steps you should take:
1. Immediately Change Your UPI PIN or Password: If you have shared your UPI PIN, open your UPI app and change it immediately. Most UPI apps have an option to change your PIN under the settings or profile section. If you have shared your password for any other account, change it as soon as possible. Use a strong, unique password that is difficult to guess.
2. Contact Your Bank: Reach out to your bank’s customer service immediately. Inform them about the incident and request them to block any suspicious transactions. You can find the customer service number on the back of your debit/credit card or on the bank’s official website. If you are unsure, visit the bank’s branch in person.
3. Report the Incident: File a complaint with the Cyber Crime Cell of the Indian government. You can do this by visiting the official website cybercrime.gov.in and following the instructions to report the fraud. Alternatively, you can call the National Cyber Crime Helpline at 1930 for immediate assistance.
4. Monitor Your Accounts: Keep a close eye on your bank statements and transaction history for any unauthorized activity. If you notice any suspicious transactions, report them to your bank immediately.
Here are some additional precautions you can take to protect yourself:
- Enable Two-Factor Authentication (2FA): This adds an extra layer of security to your accounts by requiring a second form of verification.
- Be Cautious of Phishing Attempts: Be wary of unsolicited calls, messages, or emails asking for your personal or financial information. Legitimate organizations will never ask for your sensitive information through these channels.
- Regularly Update Your Apps and Software: Keeping your apps and devices updated ensures you have the latest security patches and reduces the risk of vulnerabilities being exploited.
| Factor | UPI PIN | OTP |
|---|---|---|
| Purpose | Authenticates UPI transactions | Verifies identity for various online transactions |
| Length | 4 or 6 digits | Usually 4 to 6 digits, can vary |
| Validity | Until changed by user | Typically valid for a short period (e.g., 5 minutes) |
| Usage | Specific to UPI apps | Used across multiple platforms (banking, e-commerce, etc.) |
Remember, your vigilance is your best defense against fraud. Stay informed and proactive in safeguarding your digital life.
How can you protect yourself from OTP and UPI PIN scams?
How can you protect yourself from OTP and UPI PIN scams?
One-Time Passwords (OTPs) and UPI PINs are critical for securing your online transactions, but they can also be exploited by scammers if you’re not careful. Here’s how you can protect yourself from OTP and UPI PIN scams:
1. Never share your OTPs or UPI PINs: Legitimate companies and banks will never ask for your OTP or UPI PIN via phone, email, or message. If someone asks for these details, it’s a scam. Remember, OTPs are meant for one-time use and are valid only for a short period. UPI PINs are used to authenticate transactions and should be kept confidential at all times.
2. Be wary of unsolicited messages and calls: Scammers often impersonate bank officials, government agencies, or customer service representatives. They may claim there’s an issue with your account or a pending refund and ask for your OTP or UPI PIN to resolve it. Always verify the identity of the person contacting you through official channels before sharing any sensitive information.
3. Enable two-factor authentication (2FA): Many apps and services offer 2FA, which adds an extra layer of security. Even if a scammer gets your OTP, they won’t be able to access your account without the second factor, which could be a fingerprint, a face ID, or a secondary password.
4. Regularly monitor your account activity: Frequently check your bank and UPI app transaction history for any unauthorized activity. If you notice any suspicious transactions, report them to your bank immediately.
Here are some additional tips to stay safe:
- Use strong, unique passwords for all your accounts and change them regularly.
- Install reputable antivirus and anti-malware software on your devices.
- Keep your apps and operating systems updated to protect against vulnerabilities.
- Educate yourself and your family about common scams and how to avoid them.
To understand the differences between OTP and UPI PINs and how they are used, consider the following table:
| Factor | OTP | UPI PIN |
|---|---|---|
| Purpose | Authenticates a single transaction or login session | Secures and authenticates UPI transactions |
| Validity | Typically valid for a few minutes | Set by the user and used for multiple transactions |
| Sharing | Should never be shared | Should never be shared |
| Creation | Generated by the system and sent to the user | Set up by the user during registration |
If you suspect you’ve been a victim of a scam, report it to the Cyber Crime Cell at cybercrime.gov.in or call 1930 for immediate assistance.
What should you do if you suspect fraudulent activity related to your UPI PIN or OTP?
What should you do if you suspect fraudulent activity related to your UPI PIN or OTP?
If you suspect that your UPI PIN or OTP has been compromised or if you notice any unusual activity on your UPI-linked bank account, it is crucial to act quickly and follow these steps to protect yourself from potential fraud:
Immediate Actions
First and foremost, remain calm and do not panic. Quickly take the following steps:
- Change your UPI PIN immediately: Open your UPI app and change your UPI PIN to prevent further unauthorized transactions. Most UPI apps have an option to change the PIN under the security settings.
- Contact your bank: Reach out to your bank’s customer service immediately. Inform them about the suspected fraudulent activity and request them to block your UPI transactions temporarily. You can find the customer service number on the back of your debit/credit card or on the bank’s official website.
- Report to cybercrime authorities: File a complaint with the National Cyber Crime Reporting Portal at cybercrime.gov.in. You can also call the national helpline number 1930 to report the incident.
- Check your account statements: Review your recent account statements to identify any unauthorized transactions. Report all suspicious activities to your bank.
Additional Precautions
After taking the immediate steps, consider the following precautions to further secure your accounts:
- Update your mobile and UPI app: Ensure that your smartphone’s operating system and your UPI app are up-to-date. App updates often include security patches that protect against vulnerabilities.
- Enable two-factor authentication (2FA): If your bank or UPI app offers 2FA, enable it. This adds an extra layer of security to your transactions.
- Monitor your accounts regularly: Keep a close eye on your bank and UPI accounts for any suspicious activity. Early detection can help minimize potential losses.
Understanding the Difference: OTP vs. UPI PIN
It’s important to understand the difference between OTP and UPI PIN to better protect yourself:
| Factor | OTP | UPI PIN |
|---|---|---|
| Purpose | One-time password for verification | Personal identification number for UPI transactions |
| Usage | Used for one transaction or session | Used for authorizing UPI transactions |
| Security | Single-use, time-limited | Persistent until changed |
By understanding these differences and taking the necessary precautions, you can better protect yourself from UPI and OTP-related fraud. Remember, vigilance is your best defense against cybercrime.
Frequently asked questions
What is an OTP and how is it used?
An OTP is a temporary code sent to your registered mobile number or email for verifying your identity during transactions. It is typically valid for a short period and is used once.
How does a UPI PIN differ from an OTP?
A UPI PIN is a 4 or 6-digit personal code you create and use to authorize UPI-based transactions, while an OTP is a temporary code sent to you for verification.
Why is it important to keep your UPI PIN and OTP secure?
Keeping your UPI PIN and OTP secure is crucial because they are key to authorizing transactions from your bank account. If they fall into the wrong hands, it can lead to unauthorized transactions and financial loss.
What should you do if you accidentally share your UPI PIN or OTP?
If you accidentally share your UPI PIN or OTP, immediately contact your bank and report the incident. Change your UPI PIN if possible and monitor your account for any suspicious activity.
How can you protect yourself from OTP and UPI PIN scams?
To protect yourself, never share your OTP or UPI PIN with anyone, even if they claim to be from your bank or a trusted entity. Be cautious of phishing attempts and verify the source before taking any action.
What should you do if you suspect fraudulent activity related to your UPI PIN or OTP?
If you suspect fraudulent activity, contact your bank immediately and report the incident. You can also file a complaint on the official cybercrime website (cybercrime.gov.in) or call the national helpline 1930 for assistance.
Targeted by a scam — or already lost money?
Act immediately: (1) call your bank and freeze the account · (2) call the national Cyber Crime Helpline 1930 · (3) file a complaint at cybercrime.gov.in · (4) visit your nearest police station. See our scam-awareness guide for step-by-step help.
Arjun Rao
Arjun Rao is the founder and Editor-in-Chief of Cyber Kannadigas. A Bengaluru-based journalist and digital-rights advocate, he has spent over a decade writing about technology, governance, and consumer protection for Indian readers. He started Cyber Kannadigas after watching family members and neighbours… Read full profile →
Stay scam-safe: alerts in your inbox
Get new scam alerts, UPI-safety tips, and digital-literacy guides weekly. Free.